What is the Wholesale Electronics Market scope and industry significance?
Our analysis indicates that the Wholesale Electronics Market anchors global technology supply chains, valued at 598.49 Billion in 2026. This sector encompasses bulk B2B distribution of consumer gadgets, semiconductors, and computing hardware, serving as the critical transactional bridge between raw silicon fabrication plants and commercial end-users worldwide.
Structural Growth Drivers and Market Restraints in the Wholesale Electronics Sector
The market is propelled by surging enterprise demand for advanced computing infrastructure and automated manufacturing. However, volatile rare-earth mineral pricing and stringent export controls imposed by agencies like the Bureau of Industry and Security act as formidable headwinds, challenging traditional supply chain velocity.
Emerging Trends Shaping Wholesale Electronics Market Industry Trends
The shift toward digital B2B procurement platforms is fundamentally altering transaction dynamics. Wholesalers now prioritize AI-driven inventory forecasting to navigate complex semiconductor shortages, directly enhancing fulfillment accuracy for high-demand electronic components.
How did the pandemic alter the Wholesale Electronics Market market size trajectory?
COVID-19 induced severe logistics gridlocks across major maritime hubs, forcing a structural reevaluation of safety stock strategies. Our research shows this disruption accelerated digital transformation, boosting long-term resilience and positioning the sector for rapid post-pandemic recovery and expansion.
Competitive Benchmarking and Market Concentration
Market concentration remains moderately fragmented, dominated by global scaling titans such as Arrow Electronics Inc. and Avnet Inc. These tier-one distributors leverage vast linecards and proprietary supply chain analytics to maintain pricing power against smaller regional suppliers.
Executive Summary of the Wholesale Electronics Market Analysis
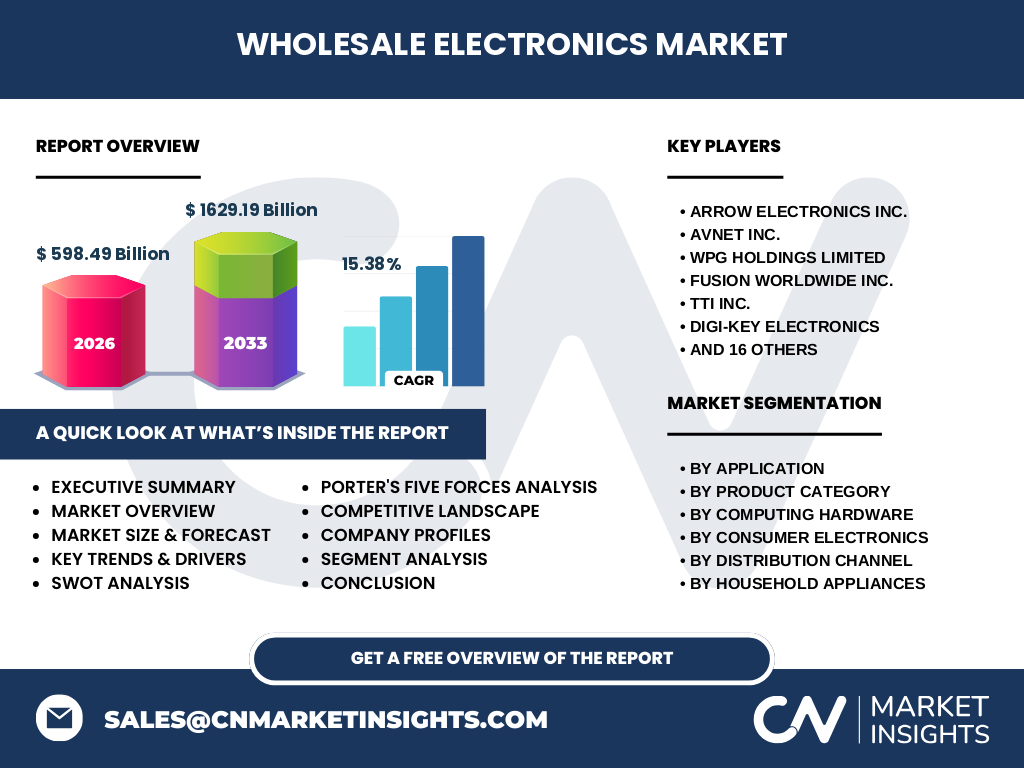
Driven by robust demand across telecommunications and industrial automation, the sector is poised for exponential expansion. Our research projects the market to surge from 598.49 Billion in 2026 to reach 1629.19 Billion by 2033, achieving a stellar CAGR of 15.38%.
Wholesale Electronics Market Forecast from 2027 to 2033
The data suggests sustained acceleration throughout the forecast window, expanding at a remarkable CAGR of 15.38%. This trajectory will elevate total market valuation from 598.49 Billion in 2026 to a commanding 1629.19 Billion by the end of 2033, driven by IoT adoption.
Segmentation Analysis Across Product Categories and Applications
The sector bifurcates into diverse categories, notably Consumer Electronics, Computing Hardware, and Electronic Components like semiconductors and PCBs. Distribution is executed via online B2B exchanges, traditional wholesalers, and manufacturer-direct channels catering to retailers, repair shops, and SMBs.
Geographic Distribution and Regional Performance Dynamics
Regional performance reflects heavy manufacturing concentrations in East Asia alongside massive enterprise demand across North America and Europe. Logistics efficiency through ports in Shenzhen and Singapore dictates regional fulfillment speeds, influencing local distributor profit margins significantly.
In-Depth Regional Review of Key Markets
Asia-Pacific dominates bulk manufacturing and component sourcing, supported by active players like WPG Holdings Limited and Shenzhen Lichuang E-commerce Co. Ltd. Meanwhile, North American demand is heavily sustained by defense electronics and cloud data center buildouts managed by firms like Fusion Worldwide Inc.
Strategic Positioning of Leading Companies in the Ecosystem
Industry leaders deploy distinct competitive strategies to capture market share. Entities like Digi-Key Electronics and Mouser Electronics Inc. excel in high-mix, low-volume component distribution, whereas TTI Inc. specializes in passive and interconnect products for heavy industrial applications.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of component suppliers remains high due to proprietary semiconductor fabrication technologies. However, intense rivalry among distributors like Future Electronics Inc. and RS Group plc compresses gross margins, intensifying the need for value-added engineering support services.
SWOT Analysis of the Wholesale Electronics Industry
Strengths lie in established global logistics networks and deep OEM relationships. Key weaknesses involve high working capital requirements. Opportunities abound in 5G infrastructure rollout, while geopolitical trade restrictions represent the most critical ongoing threat.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with upstream extraction of silicon, rare earths, and precious metals, progressing through wafer fabrication, PCB assembly, and wholesale aggregation. Mid-stream distributors such as Rochester Electronics LLC and NewPower Worldwide LLC ensure seamless component flow to downstream enterprise users.
High-Potential Investment Insights and Strategic Recommendations
Investors should target B2B platforms integrating automated inventory verification and trace-chain authentication. Companies investing in secure IoT component supply lines, championed by innovators like Master Electronics LLC and PEI-Genesis Inc., present superior risk-adjusted return profiles.
Conclusion and Strategic Takeaways for Industry Stakeholders
The path forward requires digital agility and supply chain diversification. With the market scaling to 1629.19 Billion by 2033, stakeholders must embrace advanced analytics and forge strategic alliances with established distributors to capture maximum value.
Research Methodology for Baseline Estimates and Data Triangulation
Our findings are derived from triangulating proprietary trade registry data, primary executive interviews with supply chain directors across Rutronik Elektronische Bauelemente GmbH and Anglia Components plc, and macroeconomic indicators from global electronics manufacturing associations.
Scope of the Report and Coverage Parameters
This report covers global wholesale transactions of hardware, consumer devices, and electronic components through 2033. Excluded from this specific scope are direct-to-consumer retail sales and raw semiconductor foundry-gate pricing prior to commercial packaging and wholesale aggregation.
Recent Developments, Strategic Partnerships, and Corporate Announcements
Recent market activities highlight aggressive M&A strategies and digital platform expansions. Firms like Powell Electronics Inc. and Heilind Electronics Inc. have formed strategic alliances to enhance localized connector distribution, while niche players optimize e-commerce frameworks for accelerated component delivery.